
Should I Top Up My Child’s CPF or Invest for Them?
Compare a child CPF top-up with keeping cash accessible or investing for the long term. The headline rate is only one part of the trade.
Explore the latest articles, insights, and resources in the Build Enough category. Stay informed with expert perspectives, trends, and practical guides.
Compare a child CPF top-up with keeping cash accessible or investing for the long term. The headline rate is only one part of the trade.
Thomson Reserve — the former Thomson View, on Bright Hill Drive in District 20 — previews in October, and the price list does not exist yet. Almost everything else already does: what you would need to earn, what the land cost and what that implies, how far above nearby resale each size of unit would sit, what the same money buys two streets away, and how far District 20 must rise for you to get out whole. All from free public data, worked out in advance, so you can walk into the gallery with the arithmetic already done.
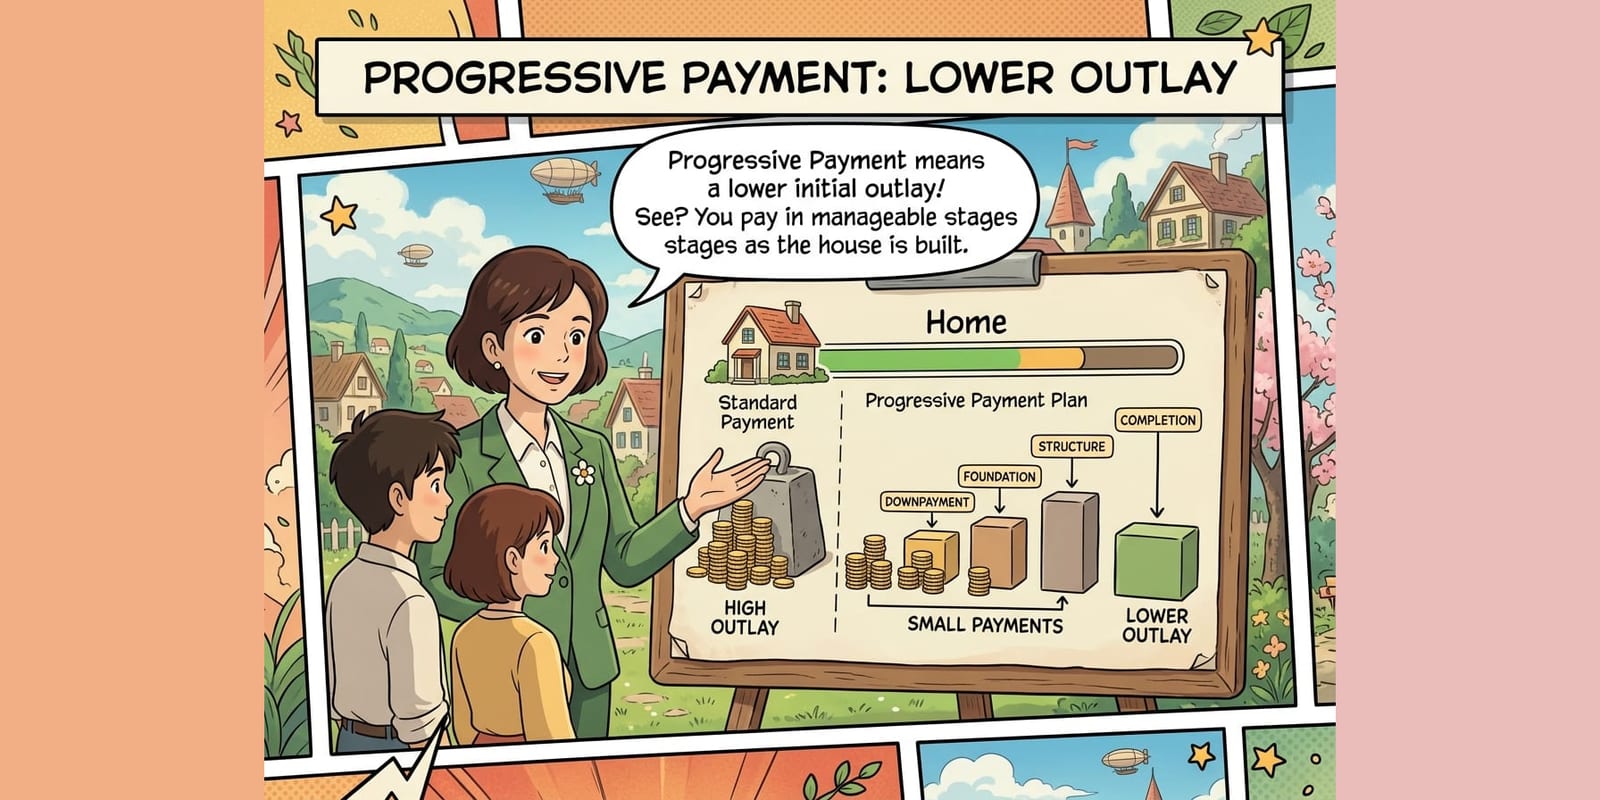
“You only pay as it is built, so it is much easier on your cash flow.” It is the most repeated line in the new-launch pitch, and it is half true. Staging the payments does save real money — about S$44,000 of interest on a S$1.5 million home. It also puts you in a rented home for three and a half years, which costs about four times that. We ran both purchases month by month for seven years. Here is where the belief holds, where it breaks, and the one situation where it is simply correct.
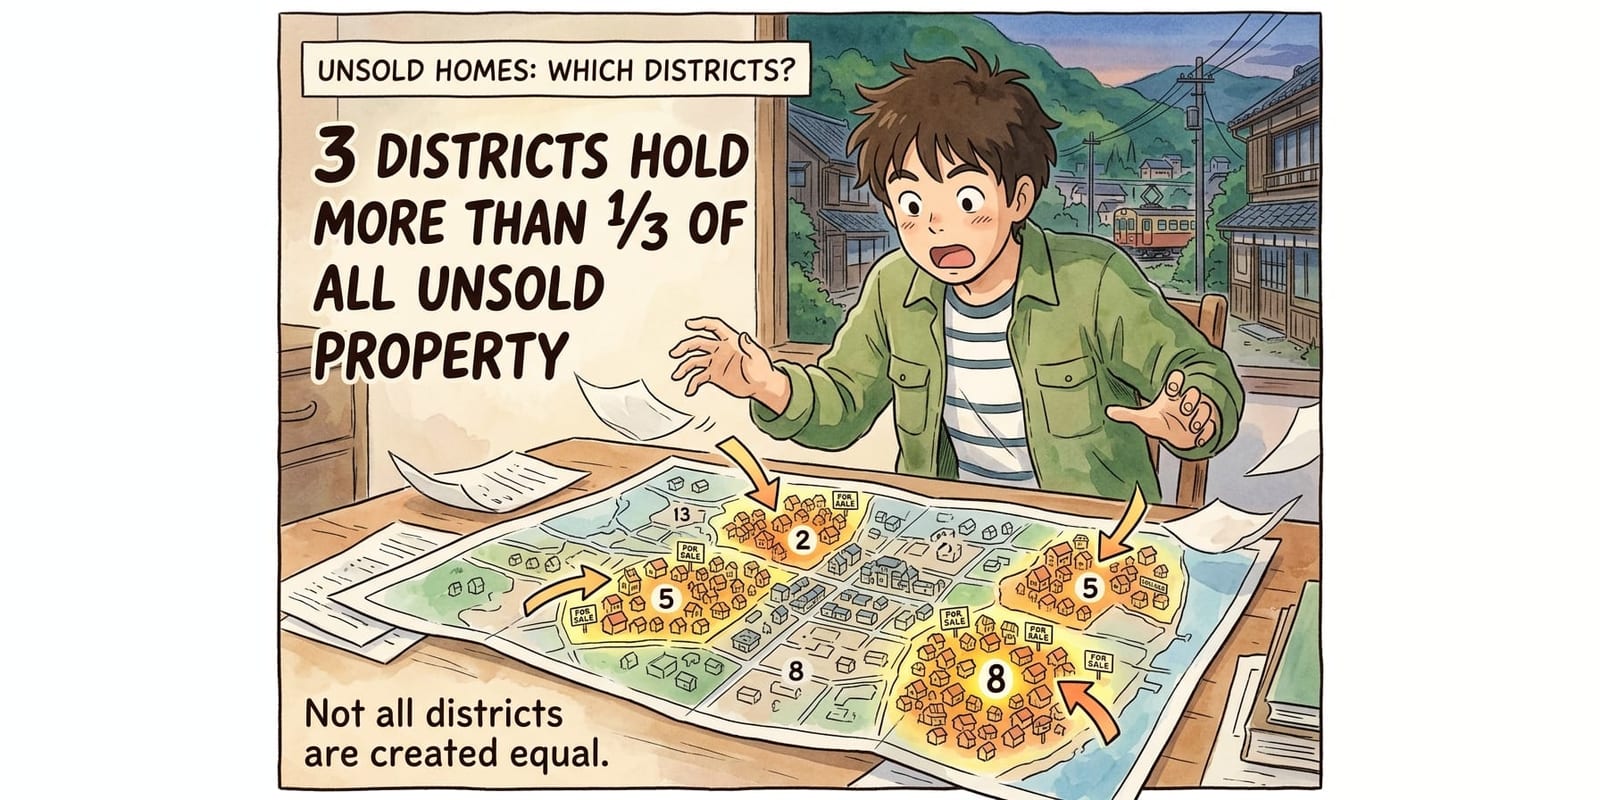
Singapore has around 34,000 unsold new private homes — developers’ stock, not resale. The figure is official, it is in every property headline this year, and it sounds like a warning about whatever you are viewing this weekend. It is also a national figure, and nobody buys the nation. We added up where the unsold stock actually sits, district by district — and it is nowhere near evenly spread. Three districts hold more than a third of it. Five have no active launch at all.
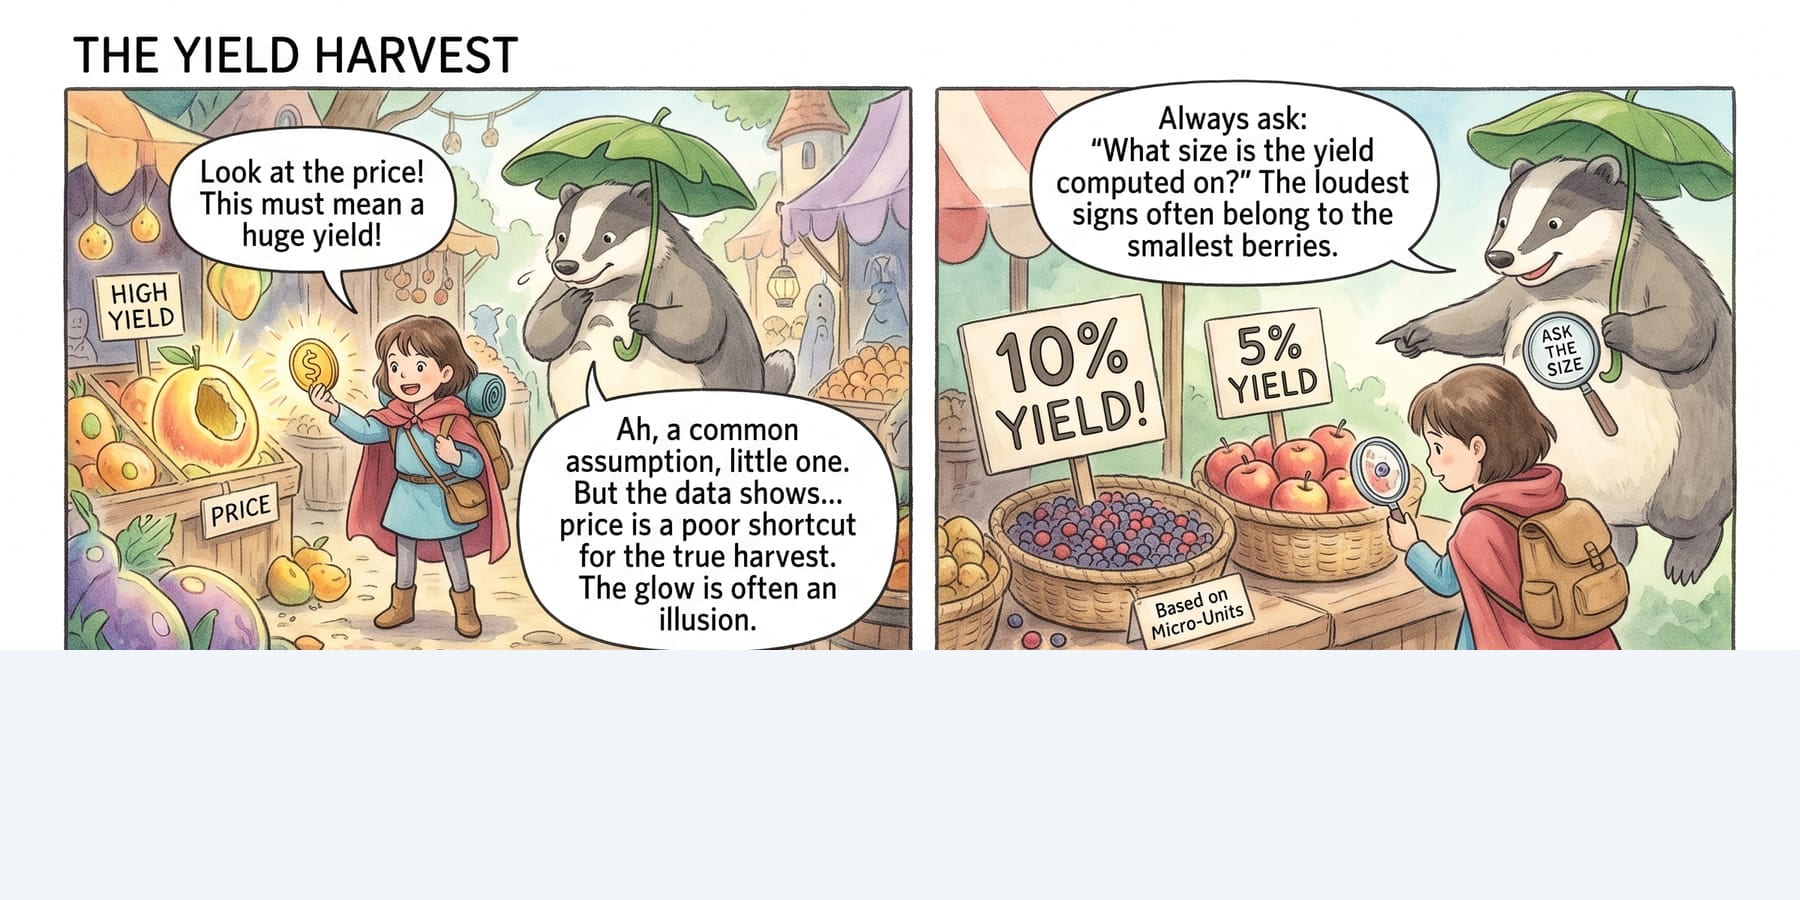
Everyone repeats the same rule: the suburbs pay you rent, the prime districts pay you prestige. We checked it across 26 of Singapore's 28 private districts and the relationship is not there — price and yield barely move together. What does move with yield is the size of the flats. The highest-yielding district in Singapore is in the city centre, and it is full of small apartments.
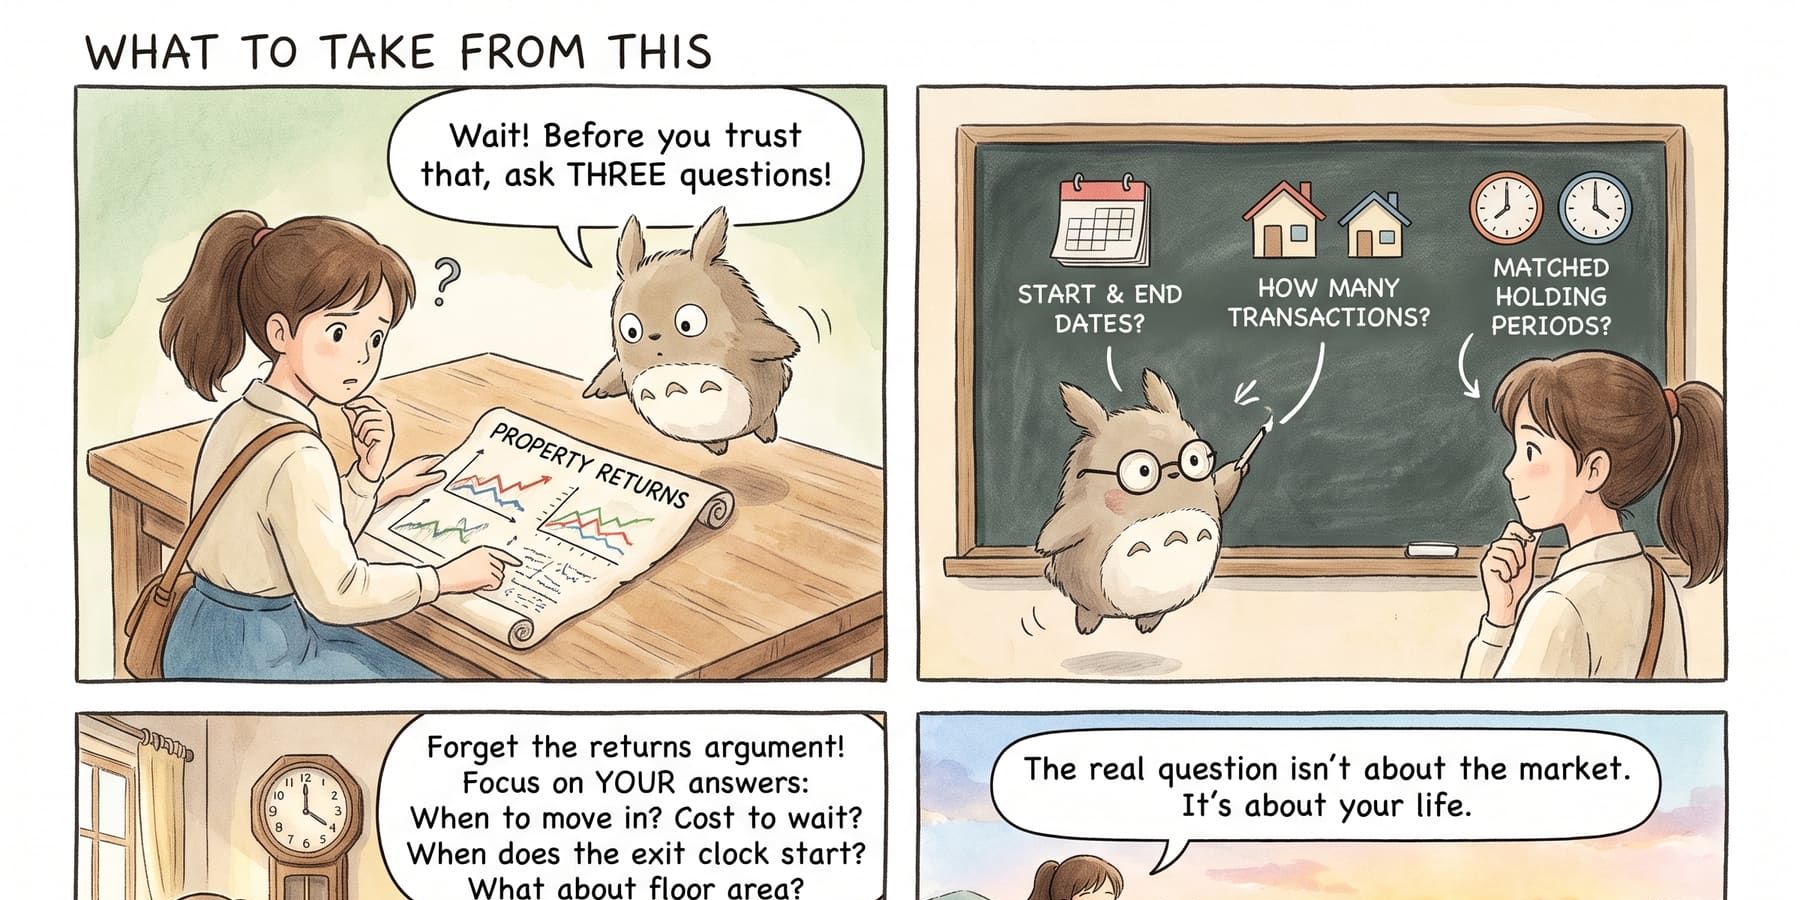
Half the property internet says good resale beats a new launch. The other half says new launches are the sure win. Both can point at real transaction data from the same source, and neither is making anything up — the answer reverses depending on where you start counting. Put both sides on the same basis and the whole advantage comes to about S$3,800 on a S$1.5 million home, against a S$44,600 stamp duty bill. Here is what is actually worth comparing instead.
A stage-based framework for laying the financial foundations that matter most in your 30s — before chasing higher-return, higher-effort strategies.
CPF top-ups and SRS contributions both offer tax relief and long-term compounding, but they behave very differently once the money is in. A framework for thinking through the trade-offs.