
Should I Top Up My Child’s CPF or Invest for Them?
Compare a child CPF top-up with keeping cash accessible or investing for the long term. The headline rate is only one part of the trade.
Read morePractical personal finance and lifestyle insights for financially aware Singaporeans — invest better, build optional income, spend with value, and reach your own enough point.
Your Enough Point
Age-based guides for every stage of your journey.
Tools We Use
Honest reviews and real calculators to help you make better money decisions.
Stories Over Coffee
Real side hustles and true stories of success from Singapore.
Value Hunts
Spend less, live better. Smart cheap hunts & tips.
Compare a child CPF top-up with keeping cash accessible or investing for the long term. The headline rate is only one part of the trade.
Read more
A bigger salary is not the same as freedom from work. Try a monthly cash-flow check, then see what changes when work income stops.
Read more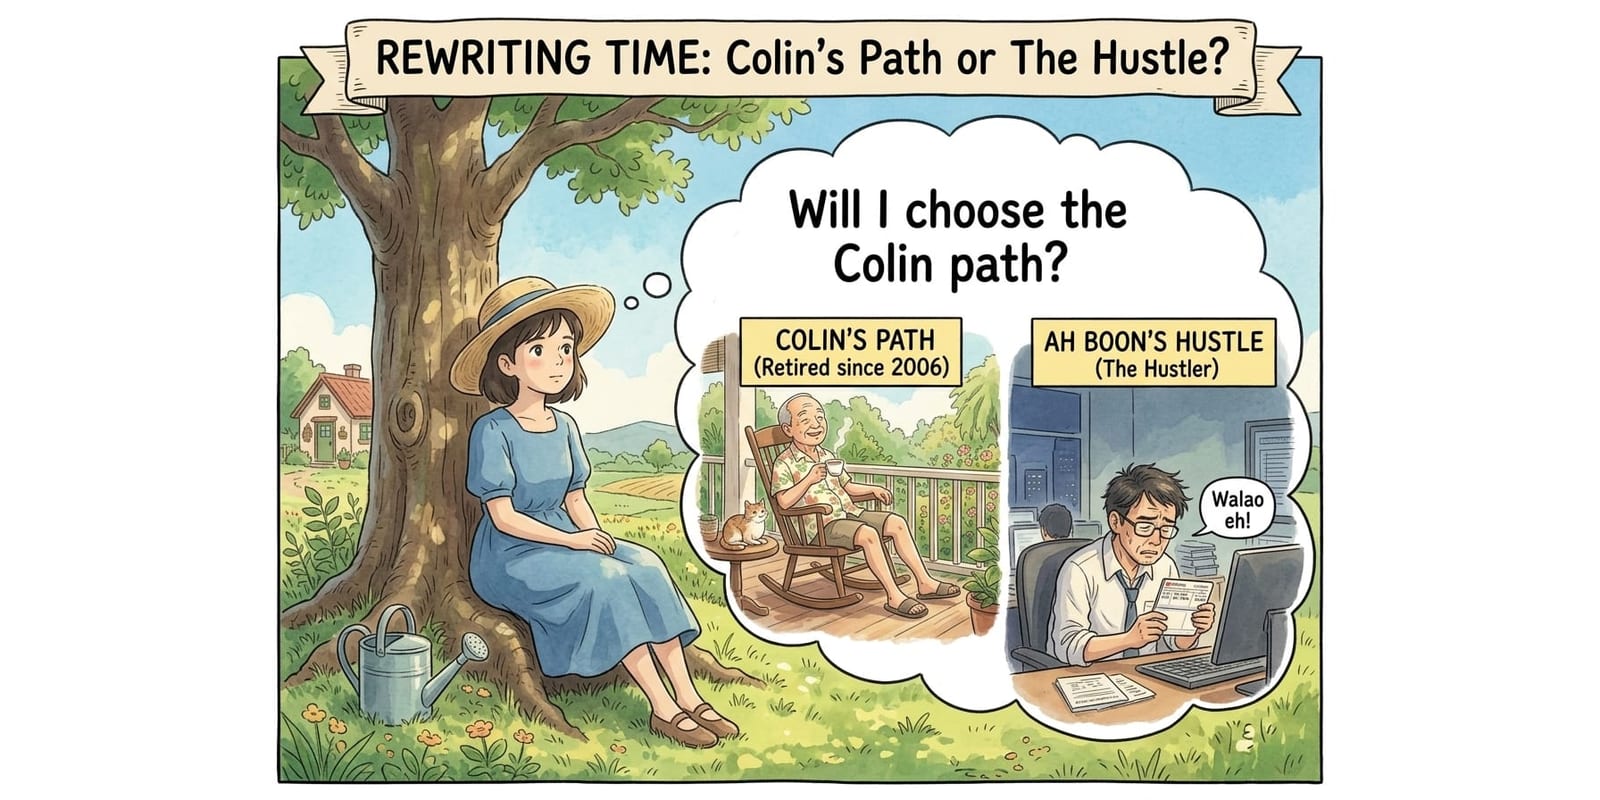
Colin Lau stopped working at 35 without first becoming rich. His choices may be too extreme for most Singaporeans, but they raise an important question: how much is enough for the life we actually want?
Read more
Somebody puts S$4,000 a month on a card advertising 4 miles per dollar, and assumes they are earning 4 miles per dollar. They are earning 1.3. Nothing went wrong and nobody was misled — the bonus rate simply stops after the first S$1,000 each month, and everything above it earns about a tenth as much. This is what that costs, why the obvious fix usually does not work, and how to tell in five minutes whether the whole exercise is beating a cashback card you could carry without thinking about it.
Read moreTools and calculators we built to help you arrive at your own enough point. Everybody's different.
Condo Side By Side Compare
Quickly compare 3 condominiums and we will let you know the pros and cons of each.
Learn moreSingapore Cashback Calendar
Shows you when to capture your next payment milestones to maximize cashback.
Learn moreThe Enough Point Check
Two scenarios side by side — what covers your household today, and what still would if work income stopped.
Learn moreComing Soon
Coming Soon
The Fed raised rates this week for the first time since 2023, and every feed has a table of what happens next. We ran all six first hikes since 1994 on free public data — US shares, gold and the STI, in Singapore dollars — with the usual outcome beside every number. The one-month dip is real; the rest is six observations.
Compare a child CPF top-up with keeping cash accessible or investing for the long term. The headline rate is only one part of the trade.
A bigger salary is not the same as freedom from work. Try a monthly cash-flow check, then see what changes when work income stops.
Colin Lau stopped working at 35 without first becoming rich. His choices may be too extreme for most Singaporeans, but they raise an important question: how much is enough for the life we actually want?
The 30-year US Treasury yield is back at levels last seen before the global financial crisis, and the headlines say the bond market is coming for shares. So we took every month since 1954 and asked what actually happened after the 10-year yield rose. The answer is calmer than the coverage — with one condition attached, and it is not the one the headlines are watching.
Anthropic has confidentially filed for an IPO, and no price exists yet. Here's how RE is thinking about the valuation math, how it compares to the SpaceX listing, the "next Google" argument, the China competition risk — and, in first person, what RE personally plans to do about it.
It is the most reasonable-sounding plan in investing: hold the cash, wait for a pullback, buy the discount. We tested it across a hundred and fifty years of market history. The problem is not that it fails when the dip comes — it is how often the dip never comes at all, and what that costs while you wait.
Somebody puts S$4,000 a month on a card advertising 4 miles per dollar, and assumes they are earning 4 miles per dollar. They are earning 1.3. Nothing went wrong and nobody was misled — the bonus rate simply stops after the first S$1,000 each month, and everything above it earns about a tenth as much. This is what that costs, why the obvious fix usually does not work, and how to tell in five minutes whether the whole exercise is beating a cashback card you could carry without thinking about it.
Get the insights that matter to your money.
Weekly, practical, Singapore-aware — no hype, no get-rich-quick language.
Disclosure
TheEnoughPoint.com is an independent publisher. We may receive compensation when you click on links to our partners. This does not influence our editorial opinions — thank you for your support.